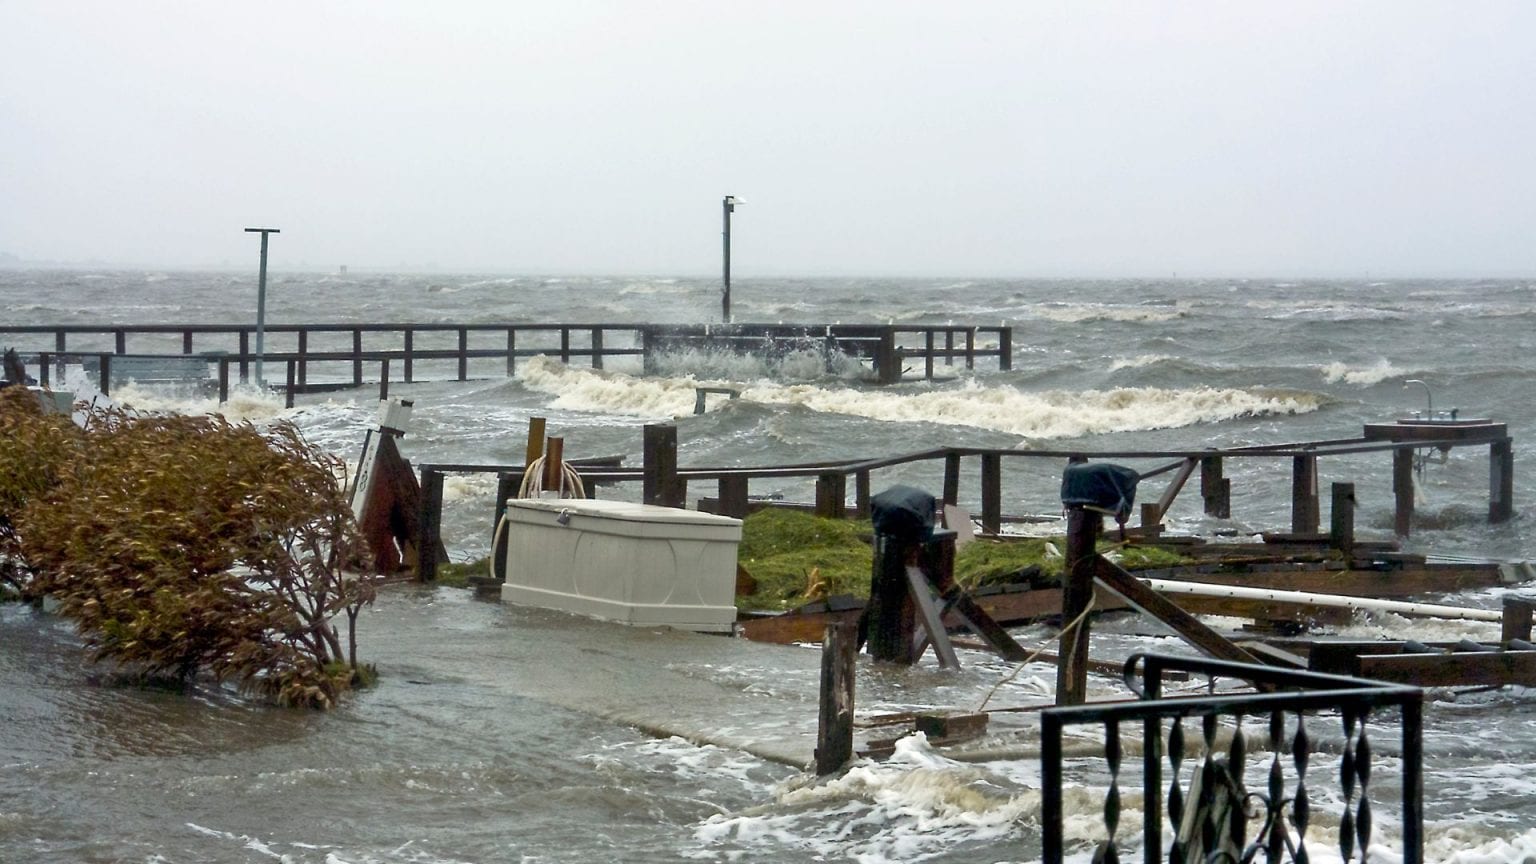
Homes in FEMA-designated flood zones typically require flood insurance to close a mortgage, and premiums can vary by thousands of dollars a year depending on zone designation, elevation, and construction type. Here’s what buyers should understand before making an offer on the Gulf Coast.
Understanding FEMA Flood Zones
FEMA flood maps divide land into zones based on flood risk. High-risk zones (often labeled “AE” or “VE”) generally require flood insurance for any home with a federally backed mortgage, while moderate- and low-risk zones (“X” zones) usually don’t carry that requirement, though flooding can still occur there. Zone designations can also change over time as FEMA updates its maps, so it’s worth checking a property’s current zone rather than relying on outdated information.
How Flood Zone Affects Insurance Costs
Premiums are driven by a combination of zone, base flood elevation, the home’s lowest floor elevation, and construction type. A home built above the base flood elevation, or one with flood vents and breakaway walls in a ground-level area, often qualifies for meaningfully lower premiums than a comparable home built at grade. Buyers should request a flood insurance quote early in the process, since it can meaningfully affect monthly housing costs.
Elevation Certificates
An elevation certificate documents a building’s elevation relative to the base flood elevation and is often required to get an accurate flood insurance quote in high-risk zones. Sellers sometimes already have one on file; if not, a licensed surveyor can prepare one. This document can be the difference between a rough estimate and an accurate, bindable insurance quote.
Working Flood Insurance Into Your Offer
Because flood insurance costs vary so much property to property, it’s worth getting a quote before finalizing an offer rather than after closing. Buyers can request flood zone and elevation information from the listing agent, and many insurance agents will provide a preliminary quote based on the property address and available flood zone data.
Frequently Asked Questions
Do all Gulf Coast homes require flood insurance?
No. Only homes with federally backed mortgages in FEMA high-risk zones are required to carry flood insurance, though many owners in moderate-risk zones choose to carry it voluntarily given the region’s flood history.
Can flood insurance costs change after I buy?
Yes. Rates can change if FEMA updates flood maps, if the property’s zone designation changes, or as NFIP pricing methodology evolves. It’s worth reviewing your policy annually.
Does a home’s flood zone affect its resale value?
It can. Buyers increasingly factor insurance costs into their budgets, so homes with lower flood risk or storm-resilient features can have an edge in the local market.
Where can I look up a property’s flood zone?
FEMA’s Flood Map Service Center allows you to search by address, and your real estate agent or insurance agent can help interpret the results.
Have questions about flood zones or insurance costs for a specific property? Explore our home buying process or learn more about hurricane-resistant home features that can also help lower insurance costs.
About The Talley Group: Our team helps buyers and sellers navigate real estate across the Alabama and Florida Gulf Coast, from Pensacola to 30A, with local expertise on everything from flood zones to community amenities.